MoneyGram Global Money Experience Combines Digital Transfers and Cash Access
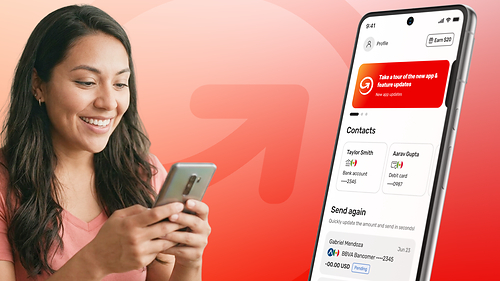
MoneyGram has launched a redesigned global consumer experience that brings international money transfers, digital balances and cash access together through its updated app and website. The move expands the company’s traditional remittance offering into a broader platform for moving, receiving, holding and using money across borders.
Announced on October 19, 2026, the refreshed MoneyGram Online experience also incorporates stablecoin-powered capabilities in selected markets. Customers can send money internationally, receive funds digitally, pay bills and top up mobile phones, while continuing to access cash through MoneyGram’s retail network.
The launch reflects a wider shift in financial services, as payment providers seek to connect digital transactions with physical cash networks. Rather than requiring consumers to navigate separate services for transfers, balances and cash collection, MoneyGram aims to bring these activities into one connected experience.
MoneyGram Global Money Experience Connects Digital and Cash Services
MoneyGram’s updated app and website are designed to give customers more flexibility in how they move and access funds. Users can initiate international transfers digitally, receive money, manage available balances and access cash through participating retail locations.
This combination addresses a practical challenge for consumers who move between digital payments and physical cash. Someone receiving money digitally may want to hold it for later use, send it to another recipient or convert it into cash when needed. Bringing these options into one experience could reduce the need to switch between different providers or services.
MoneyGram’s retail network remains an important part of the offering. The company operates across more than 200 countries and territories, with hundreds of thousands of retail locations worldwide, according to its corporate information.
The updated digital experience is intended to complement that physical infrastructure rather than replace it. Availability of individual services, however, depends on the country, local regulations and the specific payment methods supported.
MoneyGram Global Money Experience Adds Stablecoin-Powered Capabilities
Stablecoin technology is another component of the refreshed platform. Stablecoins are digital tokens designed to maintain a relatively stable value against an underlying asset, commonly a national currency such as the US dollar.
MoneyGram says customers in selected markets can maintain a stable, dollar-denominated digital balance as part of the experience. This gives eligible users another way to hold funds digitally, alongside the company’s established money-transfer and cash-access services.
The technology can operate behind the scenes, meaning consumers do not necessarily need to interact directly with blockchain systems to use the services built on them. MoneyGram’s stated goal is to manage the underlying complexity while presenting customers with a familiar interface for everyday financial tasks.
The availability of stablecoin-powered functionality is not universal. Customers should check local product terms and eligibility requirements before assuming that dollar-denominated balances or related features are accessible in their market.
The development builds on MoneyGram’s earlier work with digital assets and blockchain infrastructure, as the company looks to connect traditional payment services with newer forms of digital money.
MoneyGram Global Money Experience Expands Everyday Payment Options
Beyond cross-border transfers, the updated experience includes features for everyday financial activities. Customers can use the platform to pay bills, top up mobile phones and manage funds digitally, alongside sending and receiving money.
These functions broaden the role of the app from a transaction-focused service towards a more comprehensive money-management interface. For consumers who regularly support family members abroad or move money between countries, having several services available through one platform may simplify routine financial tasks.
However, the practical benefits depend on which services are supported in each location. Payment options, billers, currencies, transfer methods and fees can vary according to the sending and receiving markets.
MoneyGram’s strategy is to provide a consistent digital experience while drawing on its international payment network and local retail presence. That combination could be particularly relevant in markets where consumers use digital services but still rely on cash for certain transactions.
MoneyGram Global Money Experience Builds on Its International Network
MoneyGram’s physical footprint has long been central to its remittance business. The company connects customers through retail agents as well as digital channels, allowing money to move between people who may have different access to banking services.
The redesigned experience seeks to connect these channels more closely. Digital access can help customers initiate transactions and manage funds, while retail locations provide an option for cash collection and other supported services.
This model operates in a competitive market that includes digital remittance providers, banks, mobile wallets and fintech platforms. Customers increasingly expect to choose how they send, receive and use money rather than being limited to one delivery method.
A unified experience may help MoneyGram make better use of its established network, but its success will depend on ease of use, transaction costs, transfer speed, service availability and customer confidence.
Fees and exchange rates remain important considerations for international transfers. Consumers should compare the total amount paid and the amount received, rather than evaluating a service based on transfer fees alone.
MoneyGram Global Money Experience Signals a Broader Fintech Strategy
The launch illustrates MoneyGram’s effort to evolve beyond a service primarily associated with sending money overseas. By bringing transfers, digital balances, cash access and stablecoin-powered features together, the company is positioning its app and website as a broader destination for managing money across borders.
The strategy combines established infrastructure with newer financial technology. Its retail network provides access to cash in many markets, while digital services give customers more ways to initiate transactions and manage funds. Stablecoin-powered capabilities add another option in eligible locations.
The long-term test will be how consistently these features work across countries and how effectively they meet different customer needs. Regulatory requirements, local payment infrastructure and service eligibility will continue to shape what consumers can access.
For now, MoneyGram’s redesigned global experience represents another step towards connecting digital money movement with physical cash access through a single consumer-facing platform.